Fintech & Digital Assets
PCI DSS v4: what changed for merchants and acquirers
The requirements that were "best practice" until March 2025 are now mandatory. Most of them land on payment pages, authentication and the way risk is documented.
Company profile
Four practices, twelve commodity desks and every service line in one document. Read it online or download the PDF.
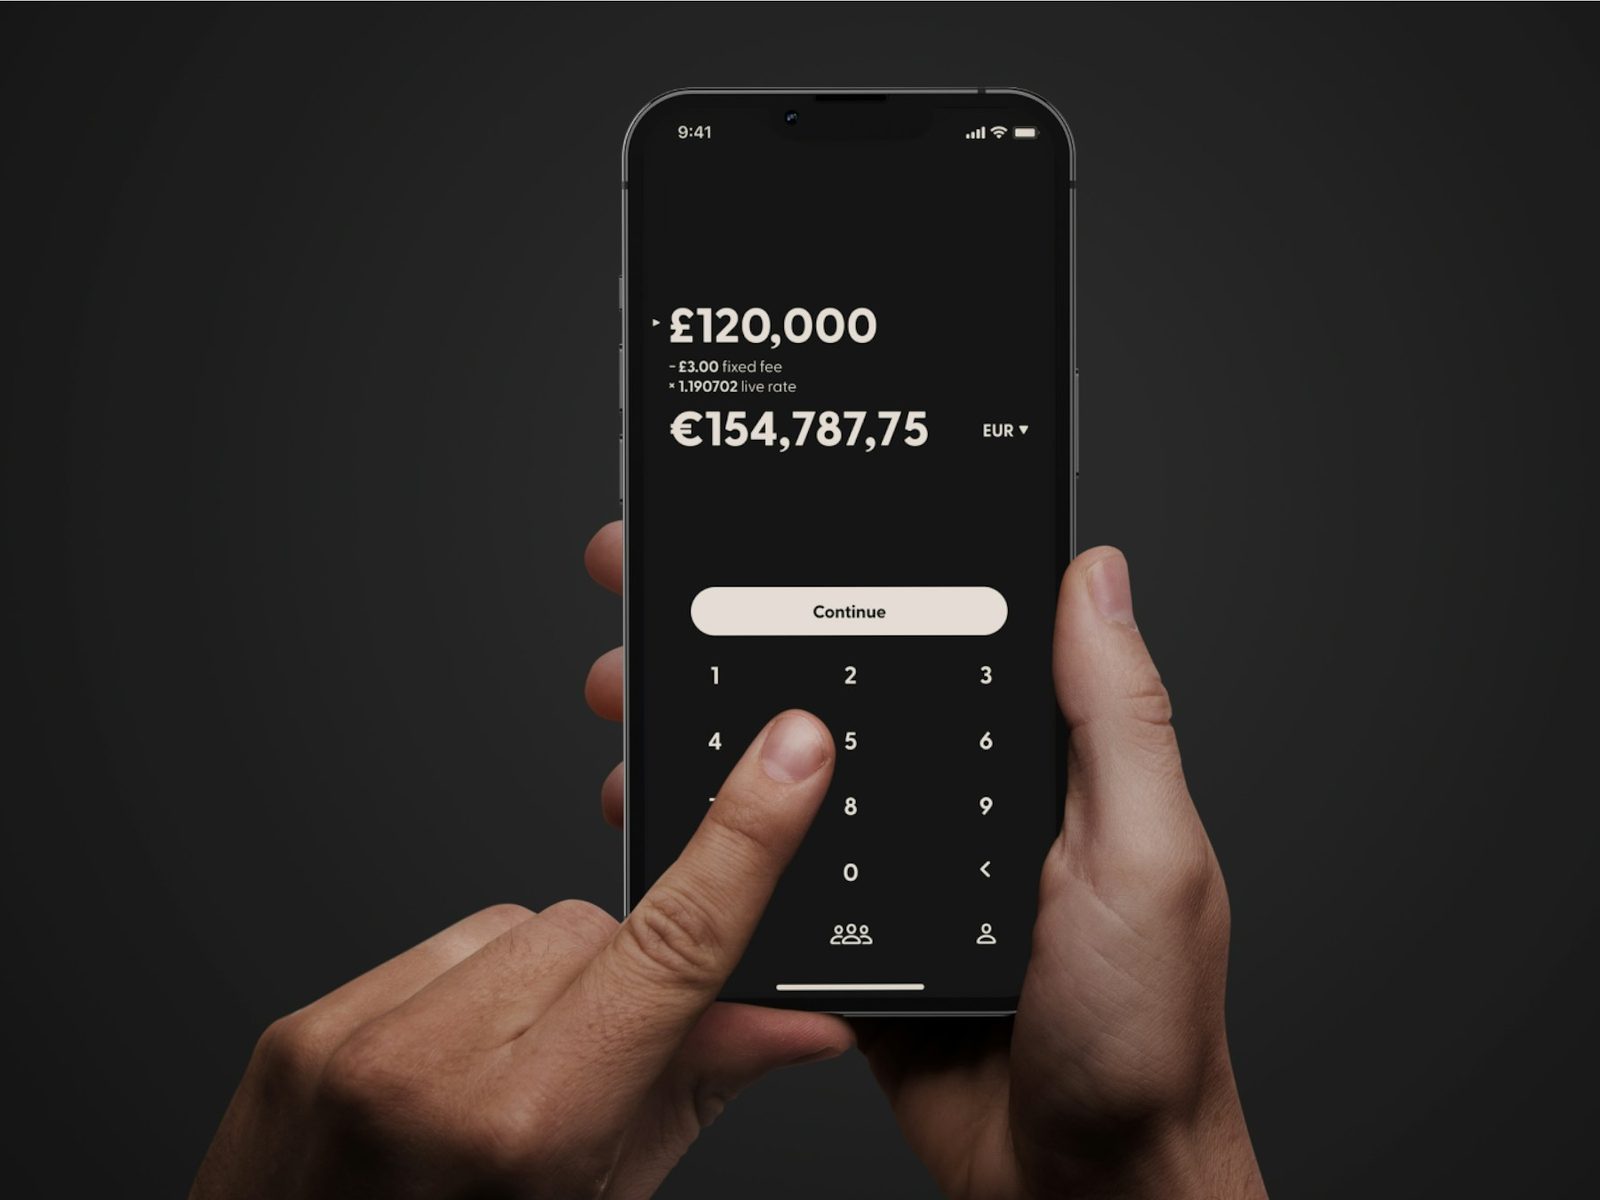
Digital banking apps, onboarding, cores and lending journeys for banks launching digital brands and companies embedding financial products.
A digital bank is judged in the first five minutes: how long it takes to open an account, whether the Arabic interface reads naturally, and whether a card arrives in the wallet before the customer closes the app. We design and build those journeys, from eKYC and liveness checks through to card provisioning and the first transfer.
Behind the app we connect to the bank's core or deploy a cloud-native ledger for a new digital brand, and we support Islamic structures such as Murabaha and Ijara with the approval workflows a Sharia board needs. The regulated balance sheet always belongs to a licensed bank; we provide the technology on top of it.
| Service | What it covers | Typical components |
|---|---|---|
| Neobank platforms | Mobile-first banking apps with accounts, cards, transfers, savings goals and Arabic-first design. | Mobile banking, Arabic-first, Personal finance |
| Digital onboarding and eKYC | Identity verification, document reading, liveness checks and risk scoring in minutes. | eKYC, Liveness, Risk scoring |
| Core and banking-as-a-service | Cloud-native cores, ledgers and APIs that let banks and brands offer financial products together. | Core banking, BaaS, Ledger |
| Islamic digital finance | Products structured on Murabaha, Ijara and Wakala models, with Sharia-board workflows. | Murabaha, Ijara, Sharia governance |
| SME and lending | Digital lending, invoice finance and buy-now-pay-later journeys with automated decisioning. | Digital lending, Invoice finance, BNPL |
We map the product, the users, the licences required and the partners who hold them.
A modular, API-first design that adds rails, currencies and assets without a rebuild.
Platform engineering and connections to banks, schemes, exchanges, custodians and blockchains.
Penetration testing, PCI and ISO controls, and audit evidence before launch.
Monitoring, reconciliation, support and continuous improvement under service levels.
Fintech & Digital Assets
The requirements that were "best practice" until March 2025 are now mandatory. Most of them land on payment pages, authentication and the way risk is documented.
Fintech & Digital Assets
Rule-based monitoring floods compliance teams with alerts that turn out to be nothing. Machine learning can cut the noise, as long as decisions stay explainable and accountable.
Fintech & Digital Assets
Cross-border payment messages have moved to ISO 20022. The richer data only helps if it is captured correctly at the counter and in the app.
Send us the details and the practice lead will reply within one business day.